

Instant Cash Advance: CashHoop
4.4

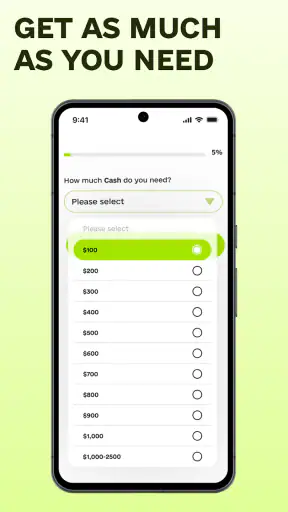
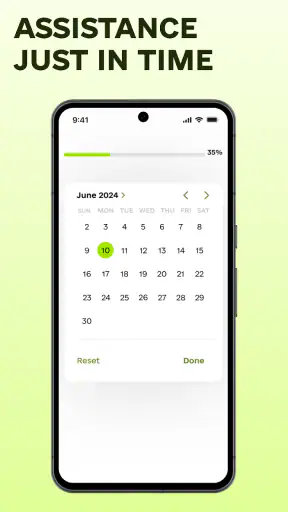
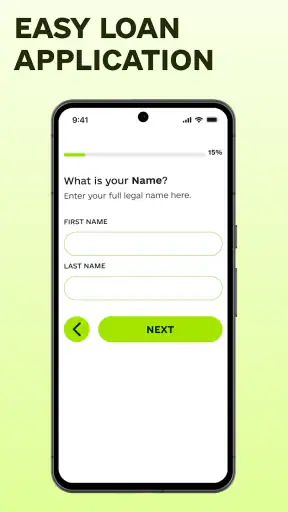
When money is tight, the hardest part is often working out whether an advance app will actually help or simply add another chore. I’d approach Instant Cash Advance: CashHoop as a short-term option to investigate, not as money I can count on before completing the app’s process. It is a free finance app from Biskup Apps, and its stated focus is getting help with expenses such as tax filing or an unexpected bill. That makes it relevant in a very specific moment: a small, near-term gap between an expense and the next payday.
Where the process can feel uncertain
The first question I would settle is whether I am comfortable sharing financial information as part of an advance application. The published review below describes connecting a bank account so the app can assess income and spending. That is a meaningful trade-off, not a minor setup detail. I would only continue if I understood what information I was authorizing and felt comfortable with the account connection; if not, I would choose a budgeting method or contact the biller directly instead.
I would also avoid treating an advance as guaranteed cash. An app may need to review an application before showing an offer, and the amount or timing can matter more than the headline promise when a bill is due today. Before relying on CashHoop for a specific payment, I would check the amount actually offered, the expected delivery timing, and the repayment arrangement shown in the app. If those details do not fit the bill’s deadline, the advance is not a dependable solution for that situation.
Checks worth making before applying
CashHoop is listed for everyone and has a 4.4 average rating from around 22,000 ratings, with more than a million installs. Those figures suggest it has reached many users, but they cannot tell me whether I will qualify or whether the terms will suit my circumstances. I would use ratings as context rather than proof that an advance will be approved or arrive on a particular schedule.
Before beginning, I would make sure I am using the current app version and that my device meets its minimum operating-system requirement. The current version is 1.0.12, and the minimum is Android 7.0. A version check is a simple first step if the app will not open or an application screen behaves unexpectedly. I would also enter personal and banking details carefully; a typo can create avoidable delays when an app needs accurate information to assess an application.
One practical habit is to read each screen before moving on rather than tapping through quickly. In a cash-advance app, the difference between an optional choice and a required step matters. I would pause at any screen that describes a transfer, repayment, or account connection, and keep a note of the amount and date I am agreeing to. That small pause helps me compare the repayment with my next paycheck instead of focusing only on the immediate cash.
Recovering when an application stalls
If a step fails, I would first identify exactly where it stopped: opening the app, entering information, connecting an account, or confirming an advance. Then I would close and reopen the app, check for an available update, and confirm that my connection is stable before trying again. Repeating the same submission several times without checking the screen or status can make it harder to tell which attempt went through.
If the issue involves a bank connection, I would check that I am selecting the right account and entering the requested details accurately, then follow the in-app prompts rather than guessing. I would not share passwords or account codes with anyone claiming to fix the issue outside the app. If the application still does not progress, I would use the app’s own support route and describe the step where it stopped, along with any message shown. That is more useful than sending a vague request for help.
A delayed transfer also calls for a little patience and a backup plan. I would check the status and the delivery option I selected before assuming something is broken. If a bill is close to its deadline, I would contact the biller and ask about an extension or another payment arrangement rather than counting on an unconfirmed transfer. A cash advance is most useful when there is enough time to understand the offer and make a second plan if it does not arrive as expected.
When the app may not be the problem
Not every blocked application points to a technical fault. The amount an app can offer may depend on the information it can review, and an offer that is smaller than expected is not necessarily something a reinstall will fix. Likewise, a bank account mismatch or incomplete information can interrupt the process even when the app itself is working. I would correct only information I know is wrong and avoid repeatedly changing details just to try to force a different result.
Timing can be outside the app’s control, too. A bank may take time to reflect a transfer, and a payment deadline may arrive before the funds do. I would not use an advance to cover an expense that has severe consequences if payment is late unless I had confirmed the delivery timing and had a backup. For a larger or recurring shortfall, I would compare other options, such as asking a provider for a payment plan or speaking with a nonprofit financial counselor, rather than stacking repeated advances.
Cash advances are also a poor fit when the next paycheck is already committed to rent, utilities, food, or other essentials. Paying a bill today by reducing the money available for necessities later can move the problem rather than solve it. I would write down the expected repayment and the bills due around that time before accepting anything. If that quick check shows the repayment would leave me short again, I would skip the advance and look for a different arrangement.
Getting Started with CashHoop
First things first, setting up CashHoop is a breeze. You download the app from either the Google Play Store or the Apple App Store, depending on your device. Once installed, the app guides you through a straightforward setup process. You'll need to provide some basic information like your name, phone number, and banking details. This might sound a bit invasive, but it's all necessary for the app's main function: getting you that cash advance.
The interface is clean and intuitive, which is always a plus. I didn’t find myself fumbling around trying to figure out what went where. Everything is clearly labeled, and the app walks you through each step. I appreciated this, as it made the whole experience feel less daunting.
How Does It Work?
Once you're all set up, using CashHoop is pretty straightforward. The app analyzes your spending habits and income to determine how much it can safely lend you without causing financial strain. This is done through a secure connection to your bank account, so make sure you’re comfortable with this level of access.
The amounts available for advance vary, but typically range from $20 to $100. While this might not seem like a lot, it's often enough to cover those unexpected expenses that pop up right before payday. The money is transferred directly to your bank account, usually within minutes if you opt for the instant transfer option.
Fees and Payback
One thing I was particularly curious about was the cost. Apps like this can sometimes have hidden fees that make them less appealing. With CashHoop, there's a small fee for the instant transfer service, but if you're willing to wait a day or two, you can skip this fee entirely. When it comes to repayment, the app automatically deducts the amount from your next paycheck, making it a hassle-free experience.
It’s worth noting that there are no interest rates involved, which is a huge relief compared to traditional payday loans. Instead, the app relies on optional tips from users to keep the service running. You get to decide how much you want to tip, if at all, which gives you control over the cost.
User Experience
As someone who values simplicity and efficiency, I was impressed by how user-friendly CashHoop is. The app doesn’t bombard you with ads or unnecessary notifications, maintaining a clean and pleasant user experience. It's designed to be quick and efficient, which is exactly what you need when you're in a financial bind.
Customer support is another area where CashHoop shines. There's a helpful FAQ section within the app, and if you still need assistance, you can reach out to their support team via email. I found their response to be prompt and helpful, which is always a plus in my book.
Everyday fit and alternatives
Think of a routine, modest surprise: a necessary household item breaks a few days before payday, and replacing it cannot wait. In that situation, I would first check whether the expense can be delayed or paid in installments. If not, an advance may bridge the gap, provided the amount offered covers the actual cost and the repayment leaves enough for essentials. That is a better use than treating available credit as extra spending money.
Compared with a credit card, an advance can be more focused on a short gap and may avoid interest, but the timing, eligibility, and repayment rules are different. A credit card may be more useful for a planned purchase when I can manage its billing cycle; CashHoop makes more sense only if its displayed terms suit an immediate need. Compared with an overdraft, the key question is the total cost and the risk of disrupting the next paycheck. I would compare the real amount due, not just whether one option sounds faster.
For a recurring shortage, neither an advance nor repeated card borrowing is a durable fix. A simple calendar of paydays and bill due dates can show whether moving a due date or setting aside a small amount each pay period would prevent the same crunch. That planning takes more time up front, but it avoids making next payday responsible for today’s problem. CashHoop is best viewed as an occasional bridge, not a substitute for that longer-term adjustment.
What I would check before deciding
A few practical questions deserve answers before I accept an offer: what exact amount will reach my account, when should it arrive, what is the total cost of the transfer choice, and when will repayment be taken? I would also check whether the repayment date matches my income schedule. The app’s general convenience matters less than those specifics, because they determine whether the advance actually fits the problem I am trying to solve.
CashHoop is free to download, but that does not mean every way of using an advance is cost-free. The instant-transfer option described above carries a fee, while waiting can avoid it; I would compare that fee with the urgency of the bill rather than choosing speed automatically. Optional tips are another decision to make deliberately. If I choose to tip, I would treat it as part of the cost when deciding whether this is better than another available option.
The app is a stronger match for someone who needs a limited, one-off cushion, is comfortable linking a bank account, and can repay without missing necessities. I would skip it if I need a large loan, if I cannot predict my next income, or if the repayment would force me to borrow again. Someone who prefers not to share banking information may also be better served by negotiating directly with a biller or asking a trusted local support service about alternatives.
Final Thoughts
Overall, Instant Cash Advance: CashHoop delivers on its promises. While it might not replace a full-blown financial safety net, it's a reliable and convenient solution for those unexpected, short-term financial hiccups. The app is straightforward, the fees are transparent, and the service is genuinely helpful.
For anyone who's ever found themselves counting down the days until payday, CashHoop offers a practical lifeline. It's not about encouraging reckless spending, but about providing a cushion when life throws a curveball. Give it a try if you're ever in need, and you might just find it becomes your go-to app for those tight spots.
My practical recommendation is to install it only when you have a specific shortfall to assess, then review the offer and repayment alongside your calendar before committing. Its Everyone age rating and simple finance focus make it accessible, but accessibility is not the same as suitability: the right choice depends on the terms shown to you and the shape of your next paycheck. Used cautiously for a genuinely temporary expense, it may be useful; used to patch a repeating budget gap, it can leave the underlying problem untouched.
4.4
1.17K Reviews
Pros
- Fast approval process for cash advances.
- User-friendly interface with clear navigation.
- No hidden fees
- transparent terms.
- Secure transactions with encryption.
- 24/7 customer support available.
Cons
- High interest rates on borrowed amounts.
- Limited to specific geographic locations.
- Requires access to personal data.
- May affect credit score with late payments.
- Not suitable for long-term financial needs.


